Optional Processes Theory and Applications
-
- Hardcover
- Taschenbuch ausgewählt
- eBook
-
Sprache:Englisch
69,99 €
inkl. gesetzl. MwSt.,
Beschreibung
Produktdetails
Einband
Taschenbuch
Erscheinungsdatum
29.04.2022
Verlag
Taylor & FrancisSeitenzahl
394
Maße (L/B/H)
23,5/19,1/2,1 cm
Gewicht
733 g
Sprache
Englisch
ISBN
978-0-367-50851-7
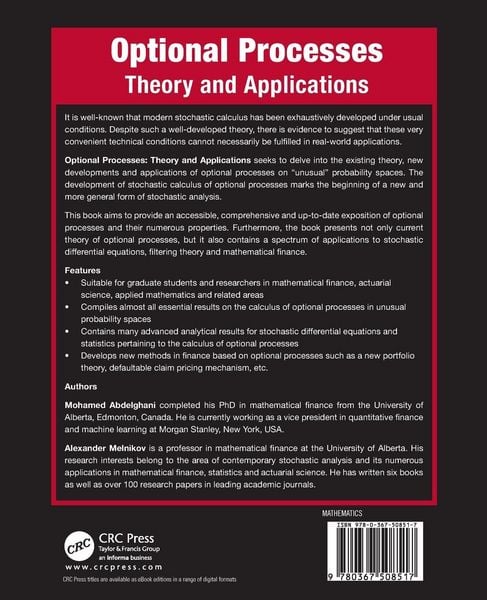
It is well-known that modern stochastic calculus has been exhaustively developed under usual conditions. Despite such a well-developed theory, there is evidence to suggest that these very convenient technical conditions cannot necessarily be fulfilled in real-world applications.
Optional Processes: Theory and Applications seeks to delve into the existing theory, new developments and applications of optional processes on "unusual" probability spaces. The development of stochastic calculus of optional processes marks the beginning of a new and more general form of stochastic analysis.
This book aims to provide an accessible, comprehensive and up-to-date exposition of optional processes and their numerous properties. Furthermore, the book presents not only current theory of optional processes, but it also contains a spectrum of applications to stochastic differential equations, filtering theory and mathematical finance.
Features
- Suitable for graduate students and researchers in mathematical finance, actuarial science, applied mathematics and related areas
- Compiles almost all essential results on the calculus of optional processes in unusual probability spaces
- Contains many advanced analytical results for stochastic differential equations and statistics pertaining to the calculus of optional processes
- Develops new methods in finance based on optional processes such as a new portfolio theory, defaultable claim pricing mechanism, etc.
Noch keine Bewertungen vorhanden
Verfassen Sie die erste Bewertung zu diesem Artikel
Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.
Kurze Frage zu unserer Seite
Vielen Dank für Ihr Feedback
Wir nutzen Ihr Feedback, um unsere Produktseiten zu verbessern. Bitte haben Sie Verständnis, dass wir Ihnen keine Rückmeldung geben können. Falls Sie Kontakt mit uns aufnehmen möchten, können Sie sich aber gerne an unseren Kund*innenservice wenden.
zum Kundenservice