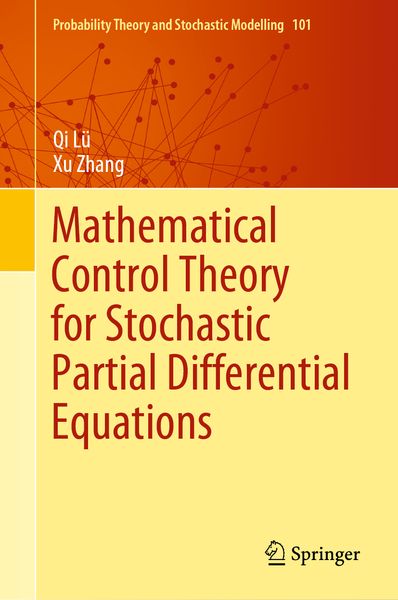
Mathematical Control Theory for Stochastic Partial Differential Equations
-
- Hardcover ausgewählt
- Taschenbuch
- eBook
-
Sprache:Englisch
159,99 €
inkl. gesetzl. MwSt.,
Beschreibung
Produktdetails
Einband
Gebundene Ausgabe
Erscheinungsdatum
18.09.2021
Abbildungen
XIII, 592 p.
Verlag
SpringerSeitenzahl
592
Maße (L/B/H)
24,1/16/3,8 cm
Gewicht
1017 g
Auflage
21001 Auflage 1st edition 2021
Sprache
Englisch
ISBN
978-3-030-82330-6
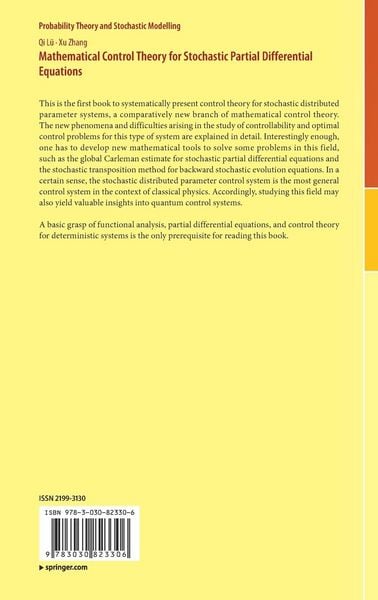
This is the first book to systematically present control theory for stochastic distributed parameter systems, a comparatively new branch of mathematical control theory. The new phenomena and difficulties arising in the study of controllability and optimal control problems for this type of system are explained in detail. Interestingly enough, one has to develop new mathematical tools to solve some problems in this field, such as the global Carleman estimate for stochastic partial differential equations and the stochastic transposition method for backward stochastic evolution equations. In a certain sense, the stochastic distributed parameter control system is the most general control system in the context of classical physics. Accordingly, studying this field may also yield valuable insights into quantum control systems.
A basic grasp of functional analysis, partial differential equations, and control theory for deterministic systems is the only prerequisite for reading this book.
Noch keine Bewertungen vorhanden
Verfassen Sie die erste Bewertung zu diesem Artikel
Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.
Kurze Frage zu unserer Seite
Vielen Dank für Ihr Feedback
Wir nutzen Ihr Feedback, um unsere Produktseiten zu verbessern. Bitte haben Sie Verständnis, dass wir Ihnen keine Rückmeldung geben können. Falls Sie Kontakt mit uns aufnehmen möchten, können Sie sich aber gerne an unseren Kund*innenservice wenden.
zum Kundenservice