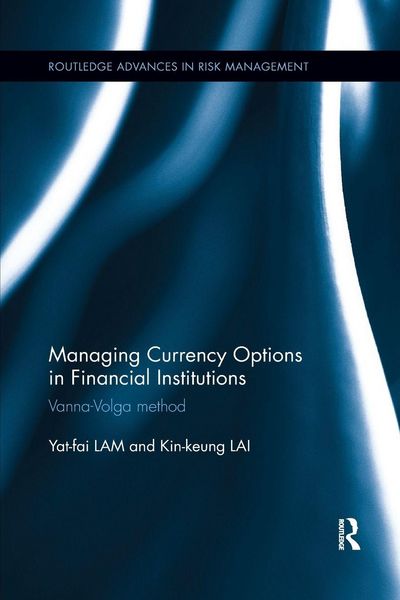
Managing Currency Options in Financial Institutions Vanna-Volga method
-
- Hardcover
- Taschenbuch ausgewählt
- eBook
-
Sprache:Englisch
88,99 €
inkl. gesetzl. MwSt.,
Beschreibung
The book introduces how we can manage currency options with the Vanna-Volga method. It describes the underlying theories and applications of the Vanna-Volga method in managing currency options of a financial institution, conforming to the Basel III regulatory requirements which demand a high consistency...
Produktdetails
| Einband |
Taschenbuch |
|---|---|
| Erscheinungsdatum |
28.06.2018 |
| Abbildungen |
schwarz-weiss Illustrationen, Zeichnungen, schwarz-weiss, Tabellen, schwarz-weiss |
| Verlag | Taylor and Francis |
Noch keine Bewertungen vorhanden
Verfassen Sie die erste Bewertung zu diesem Artikel
Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.
Kurze Frage zu unserer Seite
Vielen Dank für Ihr Feedback
Wir nutzen Ihr Feedback, um unsere Produktseiten zu verbessern. Bitte haben Sie Verständnis, dass wir Ihnen keine Rückmeldung geben können. Falls Sie Kontakt mit uns aufnehmen möchten, können Sie sich aber gerne an unseren Kund*innenservice wenden.
zum Kundenservice