• Produktbild: Stochastic Controls
  • Produktbild: Stochastic Controls
Band 43 - 12%

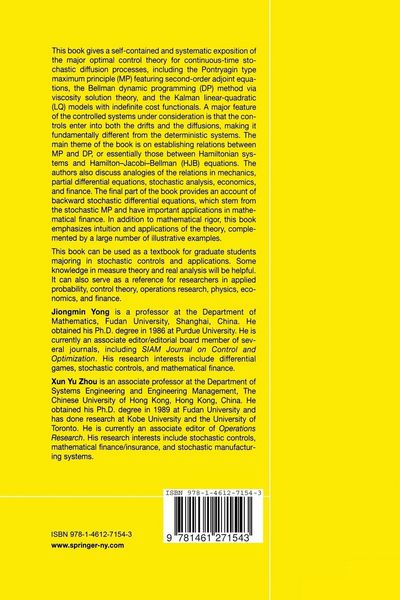
Stochastic Controls Hamiltonian Systems and HJB Equations

12% sparen

173,99 € UVP 197,99 €

inkl. gesetzl. MwSt., Versandkostenfrei


Beschreibung

Produktdetails

Einband

Taschenbuch

Erscheinungsdatum

27.09.2012

Abbildungen

XXII, 439 p.

Verlag

Springer Us

Seitenzahl

439

Maße (L/B/H)

23,5/15,5/2,5 cm

Gewicht

698 g

Auflage

Softcover reprint of the original 1st ed. 1999

Sprache

Englisch

ISBN

978-1-4612-7154-3

Beschreibung

Rezension

From the reviews:


SIAM REVIEW


"The presentation of this book is systematic and self-contained…Summing up, this book is a very good addition to the control literature, with original features not found in other reference books. Certain parts could be used as basic material for a graduate (or postgraduate) course…This book is highly recommended to anyone who wishes to study the relationship between Pontryagin’s maximum principle and Bellman’s dynamic programming principle applied to diffusion processes."


MATHEMATICS REVIEW


This is an authoratative book which should be of interest to researchers in stochastic control, mathematical finance, probability theory, and applied mathematics. Material out of this book could also be used in graduate courses on stochastic control and dynamic optimization in mathematics, engineering, and finance curricula. Tamer Basar, Math. Review

Produktdetails

Einband

Taschenbuch

Erscheinungsdatum

27.09.2012

Abbildungen

XXII, 439 p.

Verlag

Springer Us

Seitenzahl

439

Maße (L/B/H)

23,5/15,5/2,5 cm

Gewicht

698 g

Auflage

Softcover reprint of the original 1st ed. 1999

Sprache

Englisch

ISBN

978-1-4612-7154-3

Herstelleradresse

Springer-Verlag KG
Sachsenplatz 4-6
1201 Wien
AT

Email: ProductSafety@springernature.com

Noch keine Bewertungen vorhanden

Verfassen Sie die erste Bewertung zu diesem Artikel

Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.

Kundinnen und Kunden meinen

Bewertungen (0)

  • Produktbild: Stochastic Controls
  • Produktbild: Stochastic Controls
  • 1. Basic Stochastic Calculus.- 1. Probability.- 2. Stochastic Processes.- 3. Stopping Times.- 4. Martingales.- 5. Itô’s Integral.- 6. Stochastic Differential Equations.- 2. Stochastic Optimal Control Problems.- 1. Introduction.- 2. Deterministic Cases Revisited.- 3. Examples of Stochastic Control Problems.- 4. Formulations of Stochastic Optimal Control Problems.- 5. Existence of Optimal Controls.- 6. Reachable Sets of Stochastic Control Systems.- 7. Other Stochastic Control Models.- 8. Historical Remarks.- 3. Maximum Principle and Stochastic Hamiltonian Systems.- 1. Introduction.- 2. The Deterministic Case Revisited.- 3. Statement of the Stochastic Maximum Principle.- 4. A Proof of the Maximum Principle.- 5. Sufficient Conditions of Optimality.- 6. Problems with State Constraints.- 7. Historical Remarks.- 4. Dynamic Programming and HJB Equations.- 1. Introduction.- 2. The Deterministic Case Revisited.- 3. The Stochastic Principle of Optimality and the HJB Equation.- 4. Other Propertiesof the Value Function.- 5. Viscosity Solutions.- 6. Uniqueness of Viscosity Solutions.- 7. Historical Remarks.- 5. The Relationship Between the Maximum Principle and Dynamic Programming.- 1. Introduction.- 2. Classical Hamilton-Jacobi Theory.- 3. Relationship for Deterministic Systems.- 4. Relationship for Stochastic Systems.- 5. Stochastic Verification Theorems.- 6. Optimal Feedback Controls.- 7. Historical Remarks.- 6. Linear Quadratic Optimal Control Problems.- 1. Introduction.- 2. The Deterministic LQ Problems Revisited.- 3. Formulation of Stochastic LQ Problems.- 4. Finiteness and Solvability.- 5. A Necessary Condition and a Hamiltonian System.- 6. Stochastic Riccati Equations.- 7. Global Solvability of Stochastic Riccati Equations.- 8. A Mean-variance Portfolio Selection Problem.- 9. Historical Remarks.- 7. Backward Stochastic Differential Equations.- 1. Introduction.- 2. Linear Backward Stochastic Differential Equations.- 3. Nonlinear Backward Stochastic Differential Equations.- 4. Feynman—Kac-Type Formulae.- 5. Forward—Backward Stochastic Differential Equations.- 6. Option Pricing Problems.- 7. Historical Remarks.- References.