KI-Beratung Beta

Gutscheinbedingungen

**Gültig am 20.11.2026 ab einem Mindestbestellwert von 30€ auf Spielzeug, Schreibwaren, Filme, Geschenke & Trends, Musik, tolino eReader & Zubehör, Hörbücher und Hörbuch-Downloads, nicht preisgebundene Bücher und Kalender online auf thalia.at und in der Thalia App. Einzelne Artikel können ausgeschlossen sein. Aufgrund der Buchpreisbindung sind deutschsprachige Bücher und eBooks ausgenommen. Zusätzlich ausgenommen sind Abos & Flatrates, Games, Geschenkkarten/-boxen, Shelfies, Software, Zeitschriften sowie einzelne Artikel von tonies®. Pro Einkauf einmal einlösbar. Click & Collect nur bei Onlinevorabzahlung möglich. Keine Barauszahlung. Nicht kombinierbar mit anderen Aktionen und Gutscheinen. Gutschein wird auf max. 500€ Bestellwert angerechnet. Nicht gültig für Versandkosten und Services. Preisgebundene Artikel sind vom Mindestbestellwert ausgeschlossen.

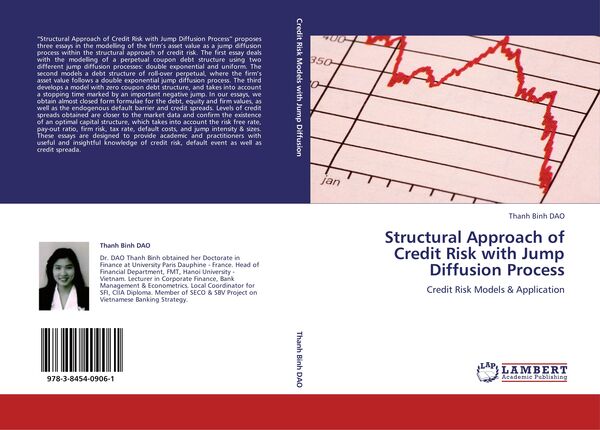
Produktbild: Structural Approach of Credit Risk with Jump Diffusion Process
- 14%

Structural Approach of Credit Risk with Jump Diffusion Process Credit Risk Models & Application

14% sparen

59,99 € UVP 70,00 €

inkl. gesetzl. MwSt., Versandkostenfrei


Beschreibung

¿Structural Approach of Credit Risk with Jump Diffusion Process¿ proposes three essays in the modelling of the firm¿s asset value as a jump diffusion process within the structural approach of credit risk. The first essay deals with the modelling of a perpetual coupon debt structure using two different...

Beschreibung

¿Structural Approach of Credit Risk with Jump Diffusion Process¿ proposes three essays in the modelling of the firm¿s asset value as a jump diffusion process within the structural approach of credit risk. The first essay deals with the modelling of a perpetual coupon debt structure using two different jump diffusion processes: double exponential and uniform. The second models a debt structure of roll-over perpetual, where the firm¿s asset value follows a double exponential jump diffusion process. The third develops a model with zero coupon debt structure, and takes into account a stopping time marked by an important negative jump. In our essays, we obtain almost closed form formulae for the debt, equity and firm values, as well as the endogenous default barrier and credit spreads. Levels of credit spreads obtained are closer to the market data and confirm the existence of an optimal capital structure, which takes into account the risk free rate, pay-out ratio, firm risk, tax rate, default costs, and jump intensity & sizes.These essays are designed to provide academic and practitioners with useful and insightful knowledge of credit risk, default event as well as credit spreada.

Produktdetails

Einband

Taschenbuch

Erscheinungsdatum

06.07.2011

Verlag LAP LAMBERT Academic Publishing
Seitenzahl

180

Produktdetails

Einband

Taschenbuch

Erscheinungsdatum

06.07.2011

Verlag LAP LAMBERT Academic Publishing
Seitenzahl

180

Maße (L/B/H)

22/15/1,1 cm

Gewicht

286 g

Auflage

1. Auflage

Sprache

Englisch

ISBN

978-3-8454-0906-1

Herstelleradresse


Email: info@bod.de

Noch keine Bewertungen vorhanden

Verfassen Sie die erste Bewertung zu diesem Artikel

Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.

Kundinnen und Kunden meinen

Bewertungen (0)

  • Produktbild: Structural Approach of Credit Risk with Jump Diffusion Process