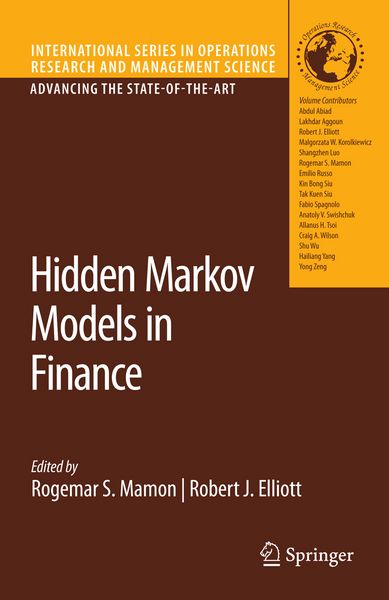
Hidden Markov Models in Finance
-
- Hardcover
- Taschenbuch ausgewählt
- eBook
-
Sprache:Englisch
-
Auflage:Softcover reprint of hardcover 1st edition 2007
65,99 €
UVP
120,99 €
inkl. gesetzl. MwSt.,
Beschreibung
Produktdetails
Einband
Taschenbuch
Erscheinungsdatum
25.11.2010
Abbildungen
XX, 186 p.
Herausgeber
Rogemar S. Mamon + weitereVerlag
Springer UsSeitenzahl
186
Maße (L/B/H)
23,5/15,5/1,2 cm
Gewicht
324 g
Auflage
Softcover reprint of hardcover 1st edition 2007
Sprache
Englisch
ISBN
978-1-4419-4380-4
A number of methodologies have been employed to provide decision making solutions to a whole assortment of financial problems in today's globalized markets.
Hidden Markov Models in Finance
by Mamon and Elliott will be the first systematic application of these methods to some special kinds of financial problems; namely, pricing options and variance swaps, valuation of life insurance policies, interest rate theory, credit risk modeling, risk management, analysis of future demand and inventory level, testing foreign exchange rate hypothesis, and early warning systems for currency crises. This book provides researchers and practitioners with analyses that allow them to sort through the random "noise" of financial markets (i.e., turbulence, volatility, emotion, chaotic events, etc.) and analyze the fundamental components of economic markets. Hence,
Hidden Markov Models in Finance
provides decision makers with a clear, accurate picture of core financial components by filtering out the random noise in financial markets.
Noch keine Bewertungen vorhanden
Verfassen Sie die erste Bewertung zu diesem Artikel
Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.
Kurze Frage zu unserer Seite
Vielen Dank für Ihr Feedback
Wir nutzen Ihr Feedback, um unsere Produktseiten zu verbessern. Bitte haben Sie Verständnis, dass wir Ihnen keine Rückmeldung geben können. Falls Sie Kontakt mit uns aufnehmen möchten, können Sie sich aber gerne an unseren Kund*innenservice wenden.
zum Kundenservice