KI-Beratung Beta

Gutscheinbedingungen

**Gültig bis 09.11.2026 auf tolino shine color (4016621130473), tolino vision color (4016621130183) und tolino vision color weiß (4016621131456) online auf thalia.at, in der Thalia App und in allen Thalia Buchhandlungen in Österreich. In den Buchhandlungen nur gültig auf lagernde Ware. Pro Einkauf einmal einlösbar. Nur gültig gegen Vorlage oder im Onlineshop hinterlegter Bonuscard. Infos zur Einlösung in der Buchhandlung sind auf der Bonuscard-Vorteilspreisseite zu finden. Click & Collect nur bei Onlinevorabzahlung möglich. Keine Einlösung bei Scan & Go-Bezahlung. Keine Barauszahlung. Nicht kombinierbar mit anderen Aktionen und Gutscheinen. Nicht gültig für Geschenkkarten, Versandkosten und Services. Nur solange der Vorrat reicht.

  • Produktbild: Nonlinear Financial Econometrics: Forecasting Models, Computational and Bayesian Models
  • Produktbild: Nonlinear Financial Econometrics: Forecasting Models, Computational and Bayesian Models

Nonlinear Financial Econometrics: Forecasting Models, Computational and Bayesian Models

49,99 €

inkl. gesetzl. MwSt., Versandkostenfrei


Beschreibung

Produktdetails

Einband

Gebundene Ausgabe

Erscheinungsdatum

21.12.2010

Abbildungen

XXIII, 195 p.

Herausgeber

G. Gregoriou + weitere

Verlag

Palgrave Macmillan UK

Seitenzahl

195

Maße (L/B/H)

22,4/14,4/2,2 cm

Gewicht

401 g

Auflage

2011 edition

Sprache

Englisch

ISBN

978-0-230-28365-7

Beschreibung

Produktdetails

Einband

Gebundene Ausgabe

Erscheinungsdatum

21.12.2010

Abbildungen

XXIII, 195 p.

Herausgeber

Verlag

Palgrave Macmillan UK

Seitenzahl

195

Maße (L/B/H)

22,4/14,4/2,2 cm

Gewicht

401 g

Auflage

2011 edition

Sprache

Englisch

ISBN

978-0-230-28365-7

Herstelleradresse

Libri GmbH
Europaallee 1
36244 Bad Hersfeld
DE

Email: gpsr@libri.de

Noch keine Bewertungen vorhanden

Verfassen Sie die erste Bewertung zu diesem Artikel

Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.

Kundinnen und Kunden meinen

Bewertungen (0)

  • Produktbild: Nonlinear Financial Econometrics: Forecasting Models, Computational and Bayesian Models
  • Produktbild: Nonlinear Financial Econometrics: Forecasting Models, Computational and Bayesian Models
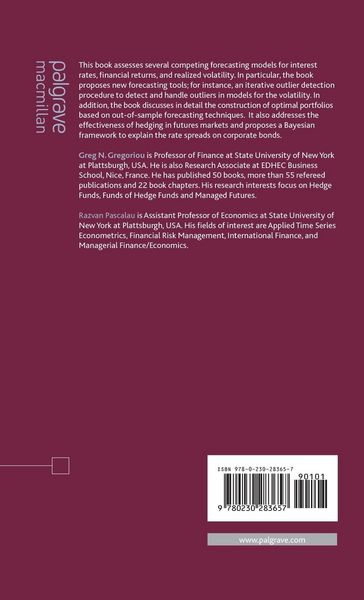
  • PART I: FORECASTING MODELS The Yield of Constant Maturity 10-Year U.S. Treasury Notes: Stumbling Towards an Accurate Forecast; R.Weißbach, W.Poniatowski & G.Zimmermann Estimating the APT Factor Sensitivities Using Quantile Regression; Z.Adams, R.Füss, P.Grüber, U.Hommel &  H.Wohlenberg Financial Risk Forecasting with Non-Stationarity; H.K.K.Tung & M.C.S.Wong International Portfolio Choice: A Spanning Approach; B.Tims & R.Mahieu Quantification of Risk and Return for Portfolio Optimization: A Comparison of Forecasting Models; N.S.Thomaidis, E.Roumpis & V.Karavas Hedging Effectiveness in The Index Futures Market; L.Copeland& Y.Zhu PART II: COMPUTATIONAL AND BAYESIAN METHODS A Bayesian Framework for Explaining the Rate Spread on Corporate Bonds; O.Chakroun & R.Ben-Abdallah GARCH, Outliers and Forecasting Volatility; P.H.Franses & D.van Dijk Is There a Relation between Discrete Time GARCH and Continuous Time Diffusion Models?; T.Bali The Recursive Fitting of Multivariate Complex Subset ARMA Models in Financial Econometrics; J.Penm & R.D.Terrell