KI-Beratung Beta

  • Produktbild: An Introduction to Financial Option Valuation
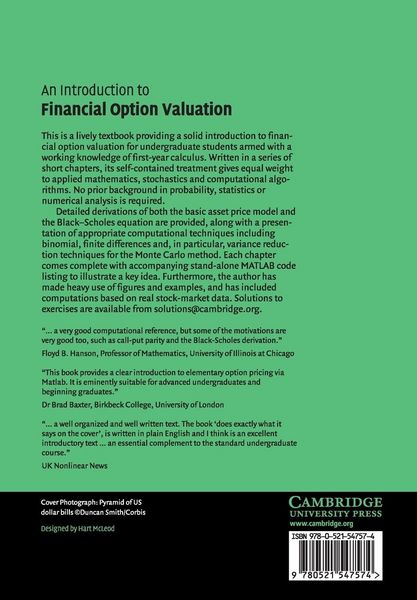
  • Produktbild: An Introduction to Financial Option Valuation

An Introduction to Financial Option Valuation Mathematics, Stochastics and Computation

89,99 €

inkl. gesetzl. MwSt., Versandkostenfrei


Beschreibung

Produktdetails

Einband

Taschenbuch

Erscheinungsdatum

26.08.2015

Verlag

Cambridge University Press

Seitenzahl

296

Maße (L/B/H)

24,4/17/1,7 cm

Gewicht

480 g

Sprache

Englisch

ISBN

978-0-521-54757-4

Beschreibung

Rezension

'... a well organized and well written text. The book 'does what it says on the cover', is written in plain English and I think is an excellent introductory text. It will be useful to students from a wide range of backgrounds and an essential complement to the standard undergraduate course which embeds mathematical finance into probability theory. Finally, with it being studded with references, it provides an easy entry into deeper material.' Chris Barnett, UK Nonlinear News

Produktdetails

Einband

Taschenbuch

Erscheinungsdatum

26.08.2015

Verlag

Cambridge University Press

Seitenzahl

296

Maße (L/B/H)

24,4/17/1,7 cm

Gewicht

480 g

Sprache

Englisch

ISBN

978-0-521-54757-4

Herstelleradresse

Libri GmbH
Europaallee 1
36244 Bad Hersfeld
DE

Email: gpsr@libri.de

Noch keine Bewertungen vorhanden

Verfassen Sie die erste Bewertung zu diesem Artikel

Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.

Kundinnen und Kunden meinen

Bewertungen (0)

Die Leseprobe wird geladen.
  • Produktbild: An Introduction to Financial Option Valuation
  • Produktbild: An Introduction to Financial Option Valuation
  • 1. Introduction; 2. Option valuation preliminaries; 3. Random variables; 4. Computer simulation; 5. Asset price movement; 6. Asset price model: part I; 7. Asset price model: part II; 8. Black-Scholes PDE and formulas; 9. More on hedging; 10. The Greeks; 11. More on the Black-Scholes formulas; 12. Risk neutrality; 13. Solving a nonlinear equation; 14. Implied volatility; 15. The Monte Carlo method; 16. The binomial method; 17. Cash-or-nothing options; 18. American options; 19. Exotic options; 20. Historical volatility; 21. Monte Carlo part II: variance reduction by antithetic variates; 22. Monte Carlo part III: variance reduction by control variates; 23. Finite difference methods; 24. Finite difference methods for the Black-Scholes PDE.