KI-Beratung Beta

Gutscheinbedingungen

**Gültig bis 31.10.2026 ab einem Mindestbestellwert von 30€ auf Spielzeug, Schreibwaren, Filme, Geschenke & Trends, Musik, tolino eReader & Zubehör, Hörbücher und Hörbuch-Downloads, nicht preisgebundene Bücher und Kalender online auf thalia.at und in der Thalia App. Einzelne Artikel können ausgeschlossen sein. Aufgrund der Buchpreisbindung sind deutschsprachige Bücher und eBooks ausgenommen. Zusätzlich ausgenommen sind Abos & Flatrates, Games, Geschenkkarten/-boxen, Shelfies, Software, Zeitschriften sowie einzelne Artikel von tonies®. Pro Einkauf einmal einlösbar. Click & Collect nur bei Onlinevorabzahlung möglich. Keine Barauszahlung. Nicht kombinierbar mit anderen Aktionen und Gutscheinen. Gutschein wird auf max. 500€ Bestellwert angerechnet. Nicht gültig für Versandkosten und Services. Preisgebundene Artikel sind vom Mindestbestellwert ausgeschlossen.

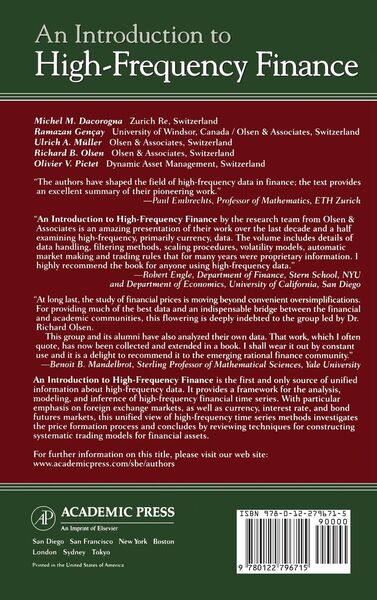
  • Produktbild: Gencay, R: Introduction to High-Frequency Finance
  • Produktbild: Gencay, R: Introduction to High-Frequency Finance

Gencay, R: Introduction to High-Frequency Finance

107,99 €

inkl. gesetzl. MwSt., Versandkostenfrei


Beschreibung

Produktdetails

Einband

Gebundene Ausgabe

Erscheinungsdatum

01.05.2001

Verlag

Elsevier LTD

Seitenzahl

410

Maße (L/B/H)

23,6/15,7/2,4 cm

Gewicht

662 g

Sprache

Englisch

ISBN

978-0-12-279671-5

Beschreibung

Rezension

Prepublication Praise:
"The authors have shaped the field of high-frequency data in finance; the text provides an excellent summary of their pioneering work." --PAUL EMBRECHTS, Professor of Mathematics, ETH Zurich

"An Introduction to High-Frequency Finance by the research team from Olsen & Associates is an amazing presentation of their work over the last decade and a half examining high-frequency, primarily currency, data. The volume includes details of data handling, filtering methods, scaling procedures, volatility models, automatic market making and trading rules that for many years were proprietary information. I highly recommend the book for anyone using tick data." --ROBERT ENGLE, Department of Finance, Stern School, NYU and Department of Economics, University of California, San Diego

"At long last, the study of financial prices is moving beyond convenient oversimplifications. For providing much of the best data and an indispensable bridge between the financial and academic communities, this flowering is deeply indebted to the group led by Dr. Richard Olsen.
This group and its alumni have also analyzed their own data. That work, which I often quote, has now been collected and extended in a book. I shall wear it out by constant use and it is a delight to recommend it to the emerging rational finance community." --BENOIT B. MANDELBROT, Sterling Professor of Mathematical Sciences, Yale University

Produktdetails

Einband

Gebundene Ausgabe

Erscheinungsdatum

01.05.2001

Verlag

Elsevier LTD

Seitenzahl

410

Maße (L/B/H)

23,6/15,7/2,4 cm

Gewicht

662 g

Sprache

Englisch

ISBN

978-0-12-279671-5

EU-Ansprechpartner

Kolibri 360 GmbH
Ettore-Bugatti-Straße 6-14
51149 Köln
DE
produktsicherheit@kolibri360.de

Herstelleradresse

A&C Black Publishers Ltd.
36 Soho Square
W1D 3QY London
UK
enquiries@acblack.com

Noch keine Bewertungen vorhanden

Verfassen Sie die erste Bewertung zu diesem Artikel

Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.

Kundinnen und Kunden meinen

Bewertungen (0)

Die Leseprobe wird geladen.
  • Produktbild: Gencay, R: Introduction to High-Frequency Finance
  • Produktbild: Gencay, R: Introduction to High-Frequency Finance
  • Introduction.
    Markets and Data.
    Time Series of Interest.
    Adaptive Data Cleaning.
    Basic Stylized Facts.
    Modeling Seasonal Volatility.
    Realized Volatility Dynamics.
    Volatility Processes.
    Forecasting Risk and Return.
    Correlation and Multivariate Risk.
    Trading Models.
    Toward a Theory of Heterogeneous Markets.
    Bibliography.
    Index.