KI-Beratung Beta

Gutscheinbedingungen

**Gültig bis 11.11.2026 auf Spielzeug, Schreibwaren, Filme, Geschenke & Trends, Musik, tolino eReader & Zubehör, Hörbücher und Hörbuch-Downloads, nicht preisgebundene Bücher und Kalender online auf thalia.at und in der Thalia App. Einzelne Artikel können ausgeschlossen sein. Aufgrund der Buchpreisbindung sind deutschsprachige Bücher und eBooks ausgenommen. Zusätzlich ausgenommen sind Abos & Flatrates, Games, Geschenkkarten/-boxen, Shelfies, Software, Zeitschriften sowie einzelne Artikel von tonies®. Pro Einkauf einmal einlösbar. Click & Collect nur bei Onlinevorabzahlung möglich. Keine Barauszahlung. Nicht kombinierbar mit anderen Aktionen und Gutscheinen. Gutschein wird auf max. 500€ Bestellwert angerechnet. Nicht gültig für Versandkosten und Services.

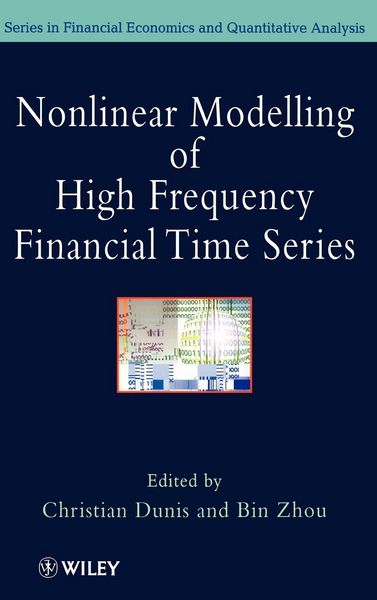
  • Produktbild: Nonlinear Modelling of High Frequency Financial Time Series
  • Produktbild: Nonlinear Modelling of High Frequency Financial Time Series

Nonlinear Modelling of High Frequency Financial Time Series

219,99 €

inkl. gesetzl. MwSt., Versandkostenfrei


Beschreibung

Nonlinear Modelling of High Frequency Financial Time Series Edited by Christian Dunis and Bin Zhou In the competitive and risky environment of today s financial markets, daily prices and models based upon low frequency price series data do not provide the level of accuracy required by traders and a growing...

Beschreibung

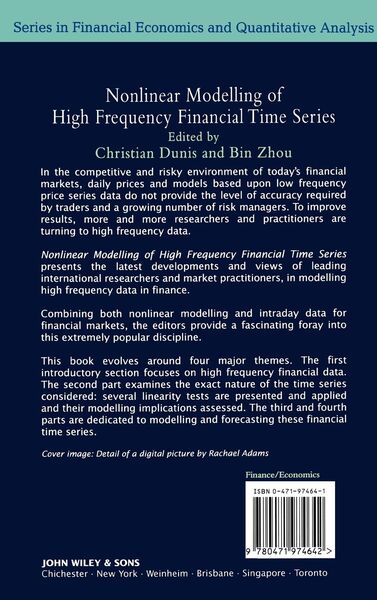
Nonlinear Modelling of High Frequency Financial Time Series Edited by Christian Dunis and Bin Zhou In the competitive and risky environment of today s financial markets, daily prices and models based upon low frequency price series data do not provide the level of accuracy required by traders and a growing number of risk managers. To improve results, more and more researchers and practitioners are turning to high frequency data. Nonlinear Modelling of High Frequency Financial Time Series presents the latest developments and views of leading international researchers and market practitioners, in modelling high frequency data in finance. Combining both nonlinear modelling and intraday data for financial markets, the editors provide a fascinating foray into this extremely popular discipline. This book evolves around four major themes. The first introductory section focuses on high frequency financial data. The second part examines the exact nature of the time series considered: several linearity tests are presented and applied and their modelling implications assessed. The third and fourth parts are dedicated to modelling and forecasting these financial time series.

Produktdetails

Einband

Gebundene Ausgabe

Erscheinungsdatum

01.10.1998

Abbildungen

w. figs.

Herausgeber Christian L. Dunis + weitere

Produktdetails

Einband

Gebundene Ausgabe

Erscheinungsdatum

01.10.1998

Abbildungen

w. figs.

Herausgeber
Verlag John Wiley & Sons
Seitenzahl

336

Maße (L/B/H)

23,5/15,7/2,4 cm

Gewicht

699 g

Auflage

1. Auflage

Sprache

Englisch

ISBN

978-0-471-97464-2

Herstelleradresse

Libri GmbH
Europaallee 1
36244 Bad Hersfeld
DE

Email: gpsr@libri.de

Noch keine Bewertungen vorhanden

Verfassen Sie die erste Bewertung zu diesem Artikel

Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.

Kundinnen und Kunden meinen

Bewertungen (0)

  • Produktbild: Nonlinear Modelling of High Frequency Financial Time Series
  • Produktbild: Nonlinear Modelling of High Frequency Financial Time Series
  • HIGH FREQUENCY MODELS IN FINANCE: MOTIVATIONS AND THEORETICAL ISSUES.
     
    Modelling with High Frequency Data: A Growing Interest for Financial Economists and Fund Managers (M. Gavridis).
     
    High Frequency Foreign Exchange Rates: Price Behavior Analysis and 'True Price' Models (J. Moody & L. Wu).
     
    DETECTING NONLINEARITIES IN HIGH FREQUENCY DATA: EMPIRICAL TESTS AND MODELLING IMPLICATIONS.
     
    Testing Linearity with Information-Theoretic Statistics and the Bootstrap (F. Acosta).
     
    Testing for Linearity: A Frequency Domain Approach (J. Drunat, et al.).
     
    Stochastic or Chaotic Dynamics in High Frequency Financial Data (D. Guégan & L. Mercier).
     
    F-consistency, De-volatization and Normalization of High Frequency Financial Data (B. Zhou).
     
    PARAMETRIC MODELS FOR NONLINEAR FINANCIAL TIME SERIES.
     
    High Frequency Financial Time Series Data: Some Stylized Facts and Models of Stochastic Volatility (E. Ghysels, et al.).
     
    Modelling Short-term Volatility with GARCH and HARCH Models (M. Dacorogna, et al.).
     
    High Frequency Switching Regimes: A Continuous-time Threshold Process (R. Dacco' & S. Satchell).
     
    Modelling Burst Phenomena: Bilinear and Autoregressive Exponential Models (J. Drunat, et al.).
     
    NON-PARAMETRIC MODELS FOR NONLINEAR FINANCIAL TIME SERIES.
     
    Application of Neural Networks to Forecast High Frequency Data: Foreign Exchange (P. Bolland, et al.).
     
    An Application of Genetic Algorithms to High Frequency Trading Models: A Case Study (C. Dunis, et al.).
     
    High Frequency Exchange Rate Forecasting by the Nearest Neighbours Method (H. Alexandre, et al.).
     
    Index.