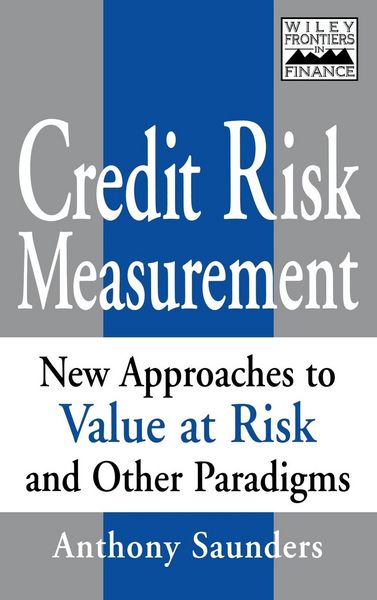
Credit Risk Measurement New Approaches to Value- At-Risk and Other Paradigms
-
- Englisch ausgewählt
-
Verlag:John Wiley & Sons
59,99 €
inkl. gesetzl. MwSt.,
Beschreibung
Produktdetails
Einband
Gebundene Ausgabe
Erscheinungsdatum
18.06.1999
Abbildungen
w. figs.
Verlag
John Wiley & SonsSeitenzahl
240
Maße (L/B/H)
23,5/15,7/1,8 cm
Gewicht
509 g
Auflage
1. Auflage
Sprache
Englisch
ISBN
978-0-471-35084-2
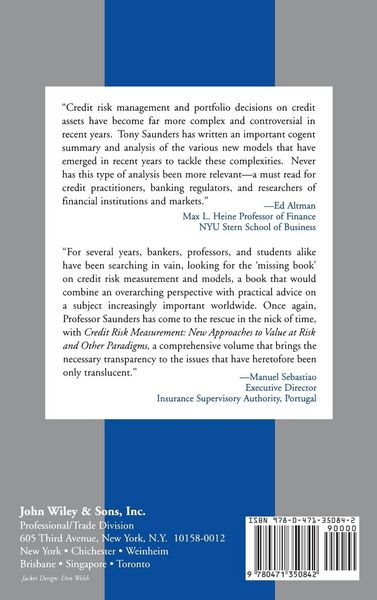
In Credit Risk Measurement: New Approaches to Value at Risk and Other Paradigms, Anthony Saunders invites a wider audience into the debate. Simplifying many of the technical details and analytics surrounding internal models, he concentrates on their underlying economics and economic intuition. Professor Saunders examines the approaches of these new models to the evaluation of individual borrower credit risk, portfolio credit risk, and derivative contracts. The alternative models explored include:
* Loans as options and the KMV model
* The VAR approach: J. P. Morgan's CreditMetrics and other models
* The macro simulation approach: the McKinsey and other models
* The risk-neutral valuation approach: KPMG's Loan Analysis System (LAS) and other models
* The insurance approach: mortality models and CSFP credit risk plus model
* Back testing and stress testing credit risk models
* RAROC models
With its comprehensive coverage, summary, and comparison of new internal model approaches along with clear explanations of often complex material, Credit Risk Measurement is an indispensable resource for bankers, academics and students, economists, and regulators.
Noch keine Bewertungen vorhanden
Verfassen Sie die erste Bewertung zu diesem Artikel
Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.
Kurze Frage zu unserer Seite
Vielen Dank für Ihr Feedback
Wir nutzen Ihr Feedback, um unsere Produktseiten zu verbessern. Bitte haben Sie Verständnis, dass wir Ihnen keine Rückmeldung geben können. Falls Sie Kontakt mit uns aufnehmen möchten, können Sie sich aber gerne an unseren Kund*innenservice wenden.
zum Kundenservice